Posts

Who is fast first to get it? Siapa cepat dia dapat?
Image
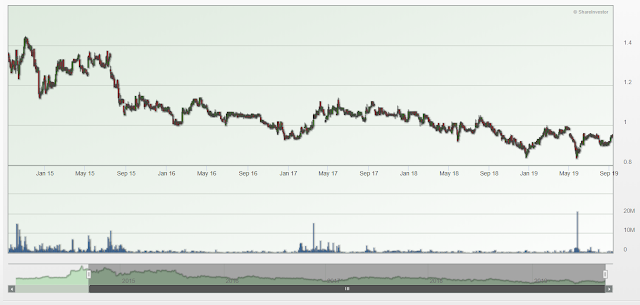
At the end of the year, most of the properties companies in Malaysia busies with home ownership campaign including OSK properties with " Siapa cepat dia dapat " (who is fast first to get it ) campaign. The Home Ownership Campaign (HOC)  is a government initiative designed to support home buyers looking to purchasing property. At the same time, it's also to encourage the sales of unsold properties in Malaysia’s housing market. The campaign was targeted to run from 1 January 2019 through to 30 June 2019, but it was recently announced by the Housing and Local Government Minister that it would be extended to 31 December 2019. At the end of the year,  also normally most investors are reviewed their investment portfolio. I think it's also for 19,220 shareholders of OSK holdings to know how well is OSK Holdings doing. If we just reviewed the trend of the stock price of OSK Holdings for the last few's year, it had been flatted below RM 1 after it's dropped since ...

Will OSK Holdings Meet the Criteria of Warren Buffet's Value Investing?

Image
One of Warren Buffet's most famous sayings is " Rule No. 1: Never lose money. Rule No. 2: Never forget rule No. 1." Another one is "If the business does well, the stock eventually follows." The third is "It's far better to buy a wonderful company at a fair price than a fair company at a wonderful price." So how can he tell us to never lose money? Buffett invests only in companies he thoroughly researches and understands. He doesn't go into an investment prepared to lose, and neither should you. There is never any complete protection from this happening. It happens to the best of us but the trick is to try to minimize your loses and protect yourself by giving yourself a margin of safety. A margin of safety is principle of investing that in which you the investor will only purchase a stock if it is below its intrinsic value. Warren Buffett used to insist on a 50% margin of safety when he was purchasing stocks. Next question. What...

What Price Should OSK Holdings Worthy of?

Image
What price should OSK Holding Berhad worthy of? Because there are no guidance reports from any analysts, let do some simple mathematics calculation. Based on the market price of cause it's just RM 0.955 per share of market cap of about RM 2 billions with a price earning ratio PE of 5.13 and NTA of RM 2.3. It's seem to be a very simple mathematics right? But what if there are some third parties or capital investment companies today announce that they want to have full acquisition of the whole business of OSK Holdings Berhad and making it private.  Then, at what price should OSK Holding Berhad worthy of? um The third parties willingness to pay a full acquisition offer of premium offer price or more than 150% of the market price of RM 1.50 per share of about a capital purchased RM 3 billions cash to own the whole OSK businesses. Are you willing to accept the deal? Is the offer price reasonable or fair? How about whether the major shareholders willing to sell at this...

Will OSK Partnership with Marubeni Success in Entering the Field of Solar Power Generation?

Image
Why are there so many listed companies want  to involve in solar power generation recently? The reason is of course the technology, cost, profitability and government policy impact of solar power generation. Global power generation trends focus on environmental protection and cost, so renewable energy is imperative. Malaysia is a country with four seasons like summer, and it is most suitable for developing solar power. If the government wants to reach the 20% target of renewable energy in 2025, it will need to invest about RM 33 billion. Putrajaya called for bids for an estimated RM2 billion worth of projects under LSS3 to increase electricity generation from renewable energy. According to Energy, Technology, Science, Climate Change and Environment Minister Yeo Bee Yin, it is an open tender and whoever give the lowest price for the first 500 megawatts (MW) and having passed all the required financial and technical qualifications will be the winner of the bidding exercise. ...

No Shame Even It Is Not Quite Fashionable and Boring....Best Yields and Investment Values..

Image
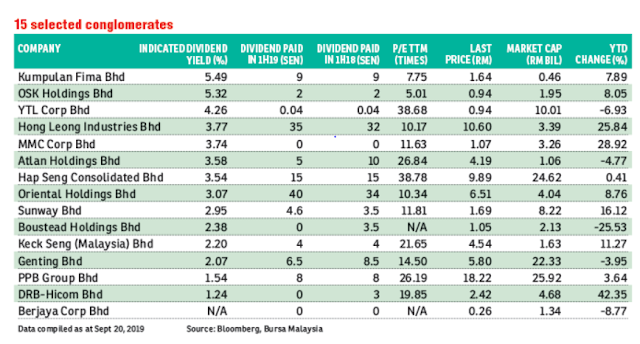
OSK Holdings Berhad is not quite fashionable as one of the 15 selected conglomerates with top two in dividend yield of 5.32% with best P/E of 5.01 not only could have good yields and very likely with full potential in capital gaining in future waiting ahead. There's no shame in losing money on a stock. Everybody does it.  What is shameful is not to hold on to a stock that obviously provide the best values and yields, or worse, to not buy more of it when it's in dip with the most under value and the fundamentals are improving and businesses are growing. It's a matter with the right timing, this stock price will fly to the sky. Source: The Edge Financial Daily  https://www.theedgemarkets.com/article/investing-conglomerates-not-quite-fashion-could-have-good-yields

An Analysis of OSK and Peer Companies

Image
From peer comparison of OSK whether with Bursa market overall investment banks/brokers or property industry, OSK is far better in term on PE, Price/NAV and Dividend Yield.  Source: Form BursaMKTPLC Alphaindicator Thomson Reuters Report  Date: 13 September 2019 OSK also performed and score much better for the last six months as compare to Ecoworld, Mahsing or UEMS.   However the OSK market price and volume had been negative returns for the last 1 to 5 years of -4.1% and -35% respectively. Will that mean huge opportunities for OSK to make a positive return soon as the business growth recently??? Source: Form BursaMKTPLC Alphaindicator Thomson Reuters Report  Date: 13 September 2019 Source: Form BursaMKTPLC Alphaindicator Thomson Reuters Report  Date: 13 September 2019 From the indicators of price momentum, valuation, fundamental & risks, OSK had an average high score as compare to many pe...

Is OSK Holdings Bhd a Value Trap or a Hidden Gem? What’s next move for OSK?

Image
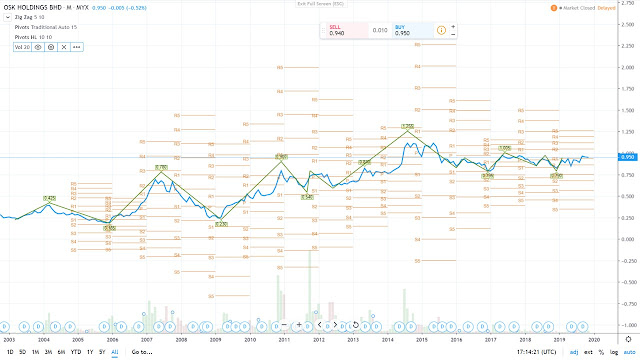
For the last five years OSK Holdings Berhad stock price had been significantly dropped in reverse of the accumulated value of NTA and business improvements. Also provide relatively decent dividend for the last 10 years but still the market undervalued the stock. Stock price RM 0.945 versus NTA of RM 2.3 NTA (after adjustment*) 2013 - RM 1.79* 2014 - RMr 1.90* (RHB - 9.9%) 2015 - RM 1.97* (OSKP-PJD merger, Bonus issue 1:4, OSK WC issue, RHB - 10.1%) 2016 - RM 2.06* 2017 - RM 2.19 (Bonus issue 1:2) 2018 - RM 2.21 2019 Q1 - RM 2.27 2019 Q2 - RM 2.3 Dividend yields 2013 - 4.55% 2014 - 3.69% 2015 - 12.27% 2016 - 5.36 % 2017 - 5.61% 2018 - 5.18% 2019 YTD - 5.29%  Any comments from any  intelligence investors?